Technical article
Getting the Date-of-death Value Right in the United States
The value is the price a willing buyer would pay a willing seller, on the date of death.
Imagine a father in Ohio who has died. He left a stamp collection, some jewelry and two paintings. His daughter is the executor. She has an insurance schedule from ten years ago and a friend who says the stamps are worth "a few thousand." She wants to put the right figure on the estate tax return and does not know what right means.
The test is plain. The value is the price a willing buyer would pay a willing seller, on the date of death. That is the wording of the Treasury regulation on household and personal effects. Each article gets its own value. Items in one room that are worth US$100 or less each may be grouped.
The numbers that matter
| Rule | What the sources state |
|---|---|
| Filing date | Form 706 is due 9 months after death. A 6-month extension to file is automatic on Form 4768. |
| Size of estate | The basic exclusion amount for 2026 is US$15,000,000. |
| Sworn appraisal | An expert's appraisal under oath for any item or collection of similar items above US$3,000. |
| Penalty | 20% when the value reported is 65% or less of the correct value. 40% when it is 40% or less. Only if the extra tax from the understatement is above US$5,000. |
| Art review | A single work appraised at US$50,000 or more is referred to IRS Art Appraisal Services. |
| Advisory panel | The Art Advisory Panel generally sees works valued above US$150,000. |
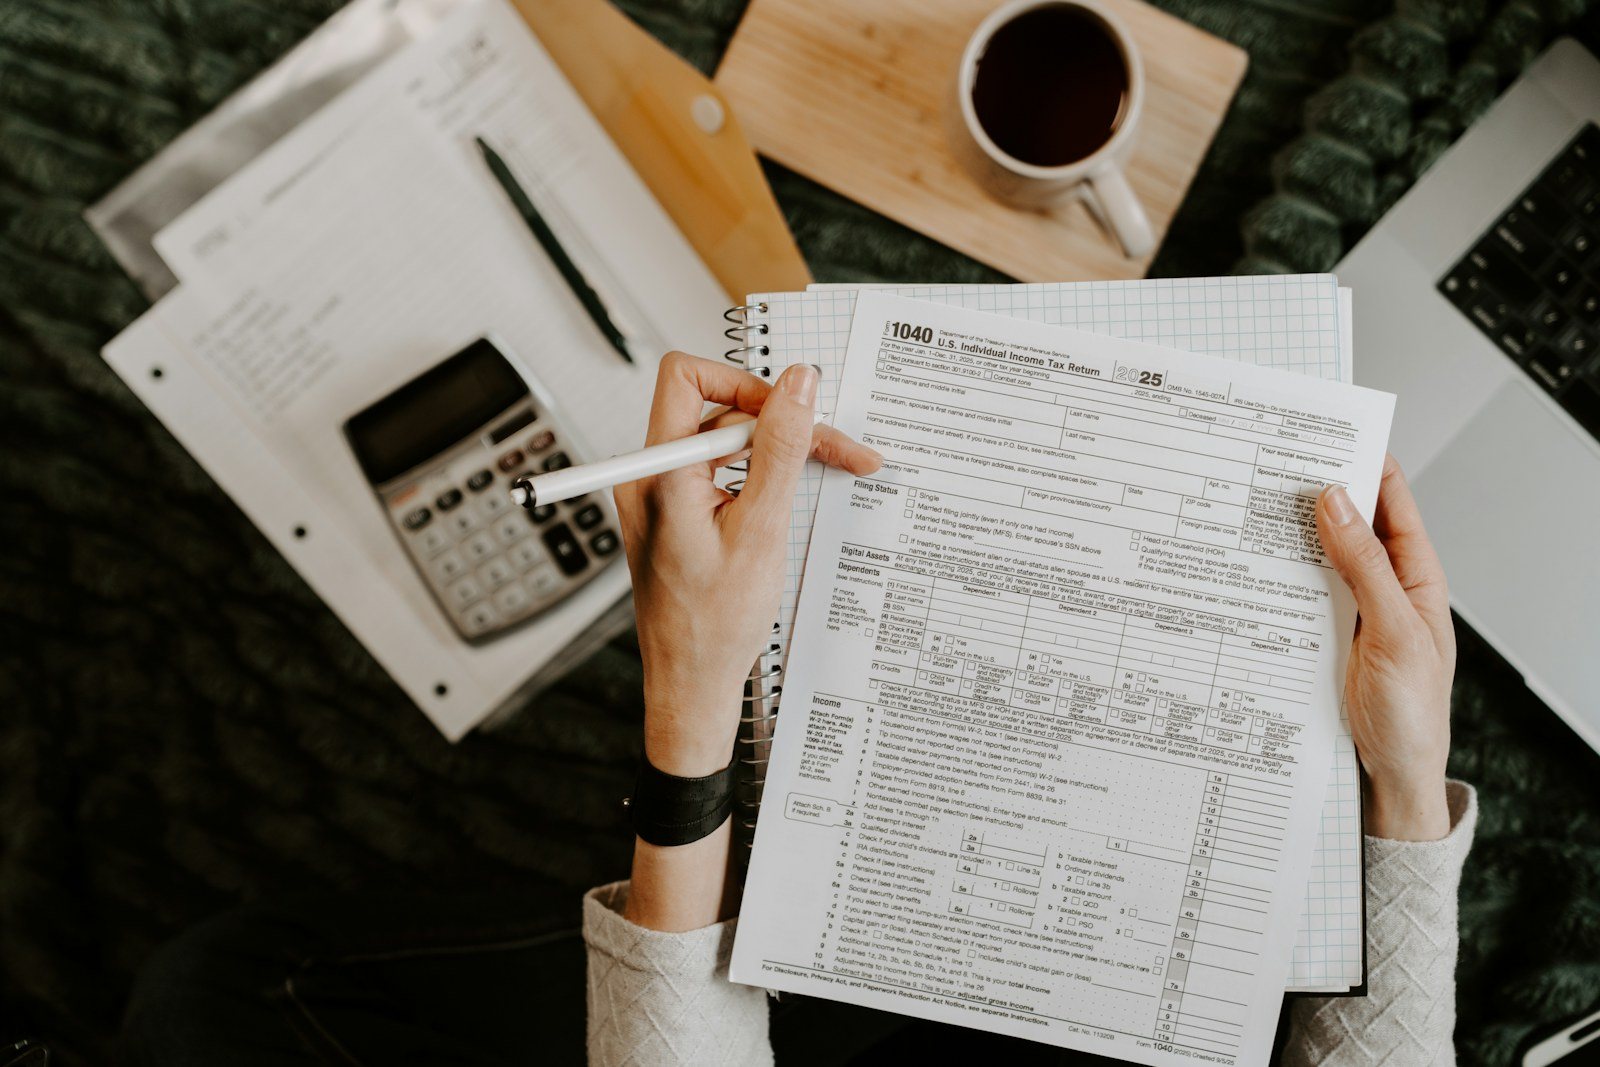
These come from the IRS instructions for Form 706, the regulation, the tax code and the IRS manual. All are official sources.
What the form asks
Schedule F of Form 706 asks whether the person owned works of art or items with collectible value. The instructions name jewelry, furs, silverware, books, statuary, vases, oriental rugs, and coin or stamp collections. The 2026 instructions also list digital assets such as cryptocurrency and digital collectibles.
The appraisal comes with a statement of the appraiser's qualifications. For art, the IRS manual lists what a good one holds: the value, the valuation date, the inspection date, a description, an image, the provenance, comparable sales, and a conservator's report if condition changes the value.
A second date
The executor may choose to value the estate six months after death. The choice is allowed only if it lowers both the gross estate and the estate tax. It cannot be undone. Property sold or distributed within those six months is valued on the day it left the estate, so a quick sale fixes the value on the sale date.
Art that draws a second look
The IRS adopted the Art Advisory Panel's recommendation in full for 103 of 206 items in fiscal year 2022. The panel gives advice, and the agency makes the final call. Panelists do not see the taxpayer's name or the tax effect.
Before filing, an executor can ask for a statement of value on art appraised at US$50,000 or more. The user fee is US$8,400 for one to three items, plus US$800 for each extra item. The agency may decline the request.
Insurance values
You might say the insurance schedule is close enough. It may be. The IRS and HM Revenue and Customs both write in terms of market value. One Canadian law-firm article notes that appraisals made for insurance often reflect replacement value, which is usually above what the estate would fetch. A schedule is a starting point for the list of what exists. It may not be the figure the form wants.
Doors you could open
You could ask an appraiser to write the value at the date of death and nothing else, so the paper matches the question. You could ask whether the fee is a flat sum or an hourly rate, since a fee tied to a percentage of value gives the appraiser a reason to raise the number. The IRS states that rule for donation appraisals, and the sources show the same ethic among appraiser bodies. You could photograph each room before anything moves.
This touches the whole family. Every heir who later sells an item starts from the value on this return. A figure that is too low now may lead to a penalty. A figure that is too high may mean tax the estate did not need to pay.
Does the US Tax My Estate if I Am a Citizen Living in Another Country? covers who is inside the estate tax at all.
Where in this list would you have started? If you have valued a parent's things, what did you wish someone had told you first? Share it here, and someone in the same chair may benefit.
Figures are estimates for planning, based on public data. Date read: October 2026.
Sources
- IRS Instructions for Form 706, 2026 (A)
- Treasury Regulation 20.2031-6 via Cornell Legal Information Institute (A)
- 26 USC 6662 and 26 USC 2032 via Cornell Legal Information Institute (A)
- IRS Internal Revenue Manual 8.18.1 (A)
- IRS Art Appraisal Services page (A)
- IRS Publication 5392 (A)
- IRS Publication 561 (A)
- Fasken article in All About Estates, March 2025 (B)
Tell us in the comments